BLS’s 4.7% July PPI: Why Wall Street’s Record Rally Is Too Comfortable
Wall Street saw 4.7% wholesale inflation and threw a party. That is not a victory lap; it is what markets do when they confuse a less-bad number with a good one.
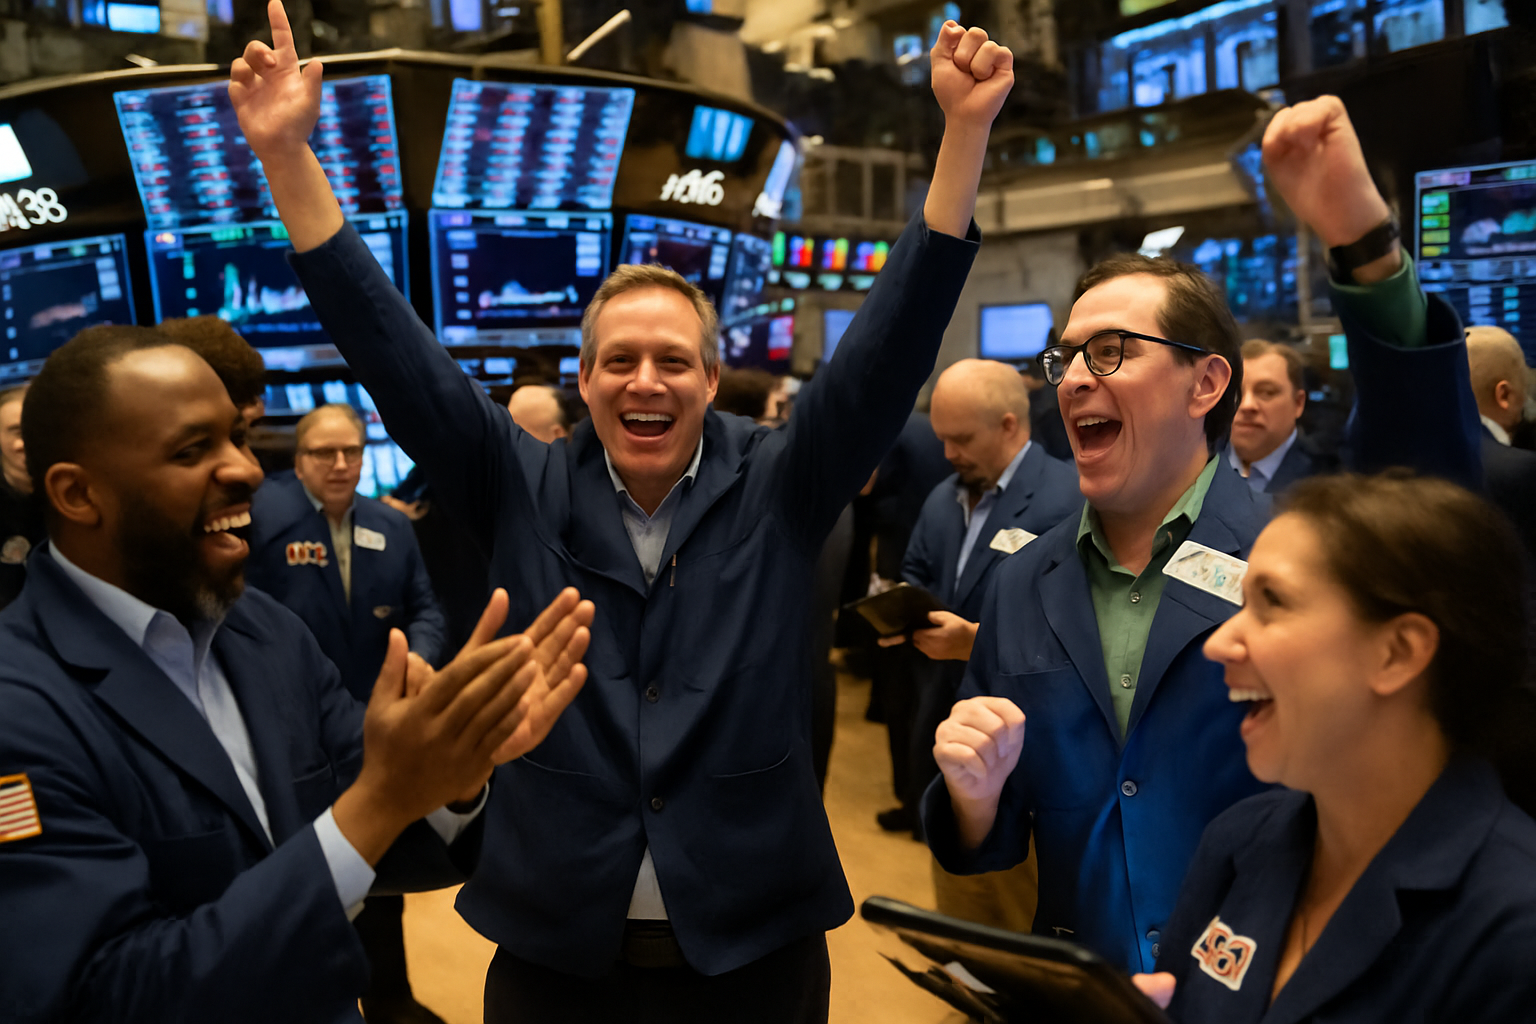
Wall Street Is Celebrating the Wrong Part of 4.7%
Wall Street saw 4.7% wholesale inflation and threw a party. That is not a victory lap; it is what markets do when they confuse a less-bad number with a good one.
The U.S. Bureau of Labor Statistics reported on August 13 that its Producer Price Index for final demand was unchanged in July, after falling 0.1% in June. On the annual measure, however, producer prices were still up 4.7%.
That is down from June’s 5.5%, and yes, the direction matters. But 4.7% is still not the sort of inflation number that makes a sensible business owner relax, lock in a big expansion plan and assume money is about to get cheap.
Markets did precisely the relaxing bit anyway. The S&P 500 rose 0.7% to a record on Thursday, August 13. The Nasdaq climbed 0.8%. Traders cut the implied chance of a Federal Reserve rate rise at the September meeting to 35%, from roughly 50% two days earlier.
That is the core story in markets today: investors are pricing relief from one cooler report while the underlying cost pressure remains far too hot for anyone running a real business to call it solved.
The July Number Was Helped by Petrol, Not a Broad Cost Collapse
Here is the bit that should make you put the champagne back in the fridge.
The headline July PPI was flat because final-demand goods prices fell 0.7%. Energy prices dropped 3.1%, and gasoline prices fell 5.7%. More than half of the decline in final-demand goods came from petrol alone.
That is helpful. Cheaper energy takes pressure off transport, households and margins. Nobody sane argues otherwise.
But it is also volatile. The same report showed that prices excluding food, energy and trade services rose 0.4% in July, after a 0.1% increase in June. Over 12 months, that measure was also up 4.7%.
In plain English: the eye-catching headline was rescued by a sharp fall in fuel. Underneath it, price pressure did not vanish. It accelerated on the month.
The services side tells the same story. Final-demand services rose 0.2% in July. Services excluding trade, transportation and warehousing rose 0.6%. Portfolio-management prices jumped 6.5%, while margins rose for retailers of health, beauty and optical goods, automobiles and auto parts, lawn and garden equipment, food and alcohol, and food-and-alcohol wholesalers.
That matters because services inflation is the sticky stuff. A business can get a lucky month on diesel. It is much harder to talk down professional fees, insurance, rents, wages, compliance costs, software bills and the endless stack of services that quietly eats your margin.
The market looked at the petrol relief. Operators should look at the 0.4% and 0.6% underneath it.
Why the S&P 500 Heard “No Rate Rise”
Markets are not stupid. They are just built to react to changes at the margin.
The annual PPI rate fell from 5.5% in June to 4.7% in July. That was better than economists expected. It arrived after a softer consumer-inflation update the day before. Oil prices also eased. Put those three things together and traders reasonably concluded the Federal Reserve has less immediate reason to raise rates.
That is why the S&P 500 hit a record. It is why technology shares got a lift. It is why the probability of a September rate increase dropped so sharply.
But there is a massive difference between the Fed may not need to tighten next month and the inflation problem is finished.
The first can be true. The second clearly is not.
A 4.7% annual wholesale-inflation rate remains well above a comfortable level. And a 0.4% monthly rise in the measure excluding food, energy and trade services is not a number you’d frame and hang above the office bar.
The BLS figures also showed final-demand construction prices rising 2.2% in July. Construction is not some irrelevant spreadsheet category. It flows into housing, commercial projects, infrastructure and the capital expenditure budgets of every operator trying to build something tangible.
If you are a founder, you do not need a PhD in macroeconomics to understand what this means. Your costs can remain stubborn even while the market cheers a benign headline. That is how budgets get blown: not through one dramatic disaster, but through a dozen suppliers each adding a little bit more.
The Second-Order Problem: Lower Energy Can Create More Demand
Here is the contrarian angle: falling energy prices can make the inflation fight harder, not easier.
Cheaper petrol helps consumers. It lowers freight costs. It lifts confidence. It gives households a bit more cash to spend elsewhere.
All good things individually.
But if consumer spending firms up while services costs are still climbing, demand can stay strong enough to keep underlying inflation sticky. That leaves the Fed in a rotten position. It cannot simply declare victory because the headline PPI had one flat month, especially when the non-energy core measures are still moving higher.
That is why I would not build an investment case around a neat sequence of rate cuts or permanently lower borrowing costs. The market is often desperate for a simple story. Right now, its story is: fuel eased, inflation eased, therefore the Fed can stand down.
Maybe. But “maybe” is not a strategy.
The more useful reading is that the economy has become highly sensitive to commodity moves. In July, a 5.7% fall in gasoline prices did a lot of heavy lifting. The Associated Press noted that petrol prices rose later in July and in early August. If that persists, August’s inflation numbers could look less friendly.
This is what catches people: they see the monthly print, then extrapolate it forever. Markets have made careers out of that mistake.
What Business Owners Should Watch Instead of the Headline
I have made enough expensive decisions to know this: broad economic headlines are useful, but your own cost base is the only inflation measure that pays your bills.
The BLS report gave a useful checklist.
Energy costs fell in July. Great. Check whether your logistics, delivery, travel and manufacturing suppliers are actually passing any of that through. Do not assume they will. Ask. Renegotiate. Send the email.
Services costs rose. That means founders and operators should audit their recurring spend now: agencies, consulting, software seats, outsourced finance, legal work, freight contracts, insurance and any vendor that has become part of the furniture because cancelling them feels annoying.
Construction prices rose 2.2%. If you have a fit-out, warehouse, property development or major equipment project in the pipeline, revisit the contingencies. A spreadsheet that assumed costs were about to settle down may be fiction.
And investors: stop treating “inflation cooling” as a blanket buy signal. The winners in this environment are businesses with real pricing power, low debt relative to cash flow, and managers who can protect margins without pretending every customer will happily wear a price increase.
The weak businesses are the ones dependent on cheap refinancing, promotional pricing, and an assumption that every input cost is about to behave.
The Overlooked Lesson: Good News Can Still Be Bad News
The July PPI report was good news relative to June. It was not objectively good news.
That distinction sounds pedantic until you are making decisions with real money.
A drop from 5.5% to 4.7% is progress. It is also a reminder that wholesale inflation is still running hot, underlying monthly prices are still rising, and the energy relief driving the headline may not be permanent.
Wall Street is allowed to celebrate reduced odds of a September rate rise. Its job is to place bets on the next move.
Your job is different. You have to survive the moves after that.
What This Means for You
Do three things tomorrow.
First, run your business or household budget at today’s borrowing costs, not at the lower rates you hope arrive later. If lower rates come, terrific. Treat them as upside, not oxygen.
Second, split your costs into energy-sensitive and sticky-service categories. If energy falls, chase the savings. If services are rising, negotiate earlier than you feel you need to. The best time to cut waste is before your margin report starts screaming.
Third, do not chase a record-high market simply because one inflation release looked less ugly. Keep buying quality assets if that is your long-term plan, but know what you own and why. A market record is not a permission slip to become careless.
The July PPI gave investors a reason to breathe out. It did not give them a reason to switch their brains off.
That is the opportunity for anyone building, investing or saving seriously: be calmer than the headlines, but more alert than the crowd.