Copart’s $1.9B ACV Deal Buys the Data, Not the Cars
Copart didn’t spend $1.9 billion to buy another car auction. It paid $10.50 a share because the used-car market is won by whoever sees a vehicle best before it moves.
Copart didn’t spend $1.9 billion to buy another car auction. It paid $10.50 a share because the used-car market is won by whoever sees a vehicle best before it moves.
That is the uncomfortable bit for anyone still treating “AI” as a slide deck garnish. The real money sits underneath the buzzwords: proprietary data collected at the ugly, expensive, high-friction point where a physical asset changes hands.
On September 10, Copart agreed to acquire ACV Auctions for $10.50 per share in cash, an implied equity value of roughly $1.9 billion. It is Copart’s largest acquisition to date, and it is a much more serious strategic move than the headline suggests.
This is a land grab across the car’s whole life
Copart built its empire around a brutally practical business: getting damaged and salvaged cars from insurers and other sellers into the hands of buyers through online auctions. It has more than 250 locations in 11 countries, roughly 1 million members across more than 185 countries, and sold more than 4 million vehicles in the last year.
That is a proper machine. Lots, logistics, seller relationships, buyers, compliance, payments, auctions. Not sexy. Very hard to replicate.
ACV comes from the other end of the vehicle’s journey. Its digital marketplace helps dealers buy and sell used cars wholesale, with inspection technology, condition reports, transport, financing and valuation tools layered into the transaction.
Put bluntly: Copart has dominated when cars are damaged, retired, repossessed or otherwise headed for a new life. ACV gives it a serious position much earlier, when dealers are deciding what a trade-in is worth, whether to keep it, retail it, wholesale it or move it fast.
The combined pitch is an end-to-end remarketing platform: dealer trade-ins, wholesale remarketing, salvage disposition and international resale. That is a far better business than simply being the bloke who auctions wrecks.
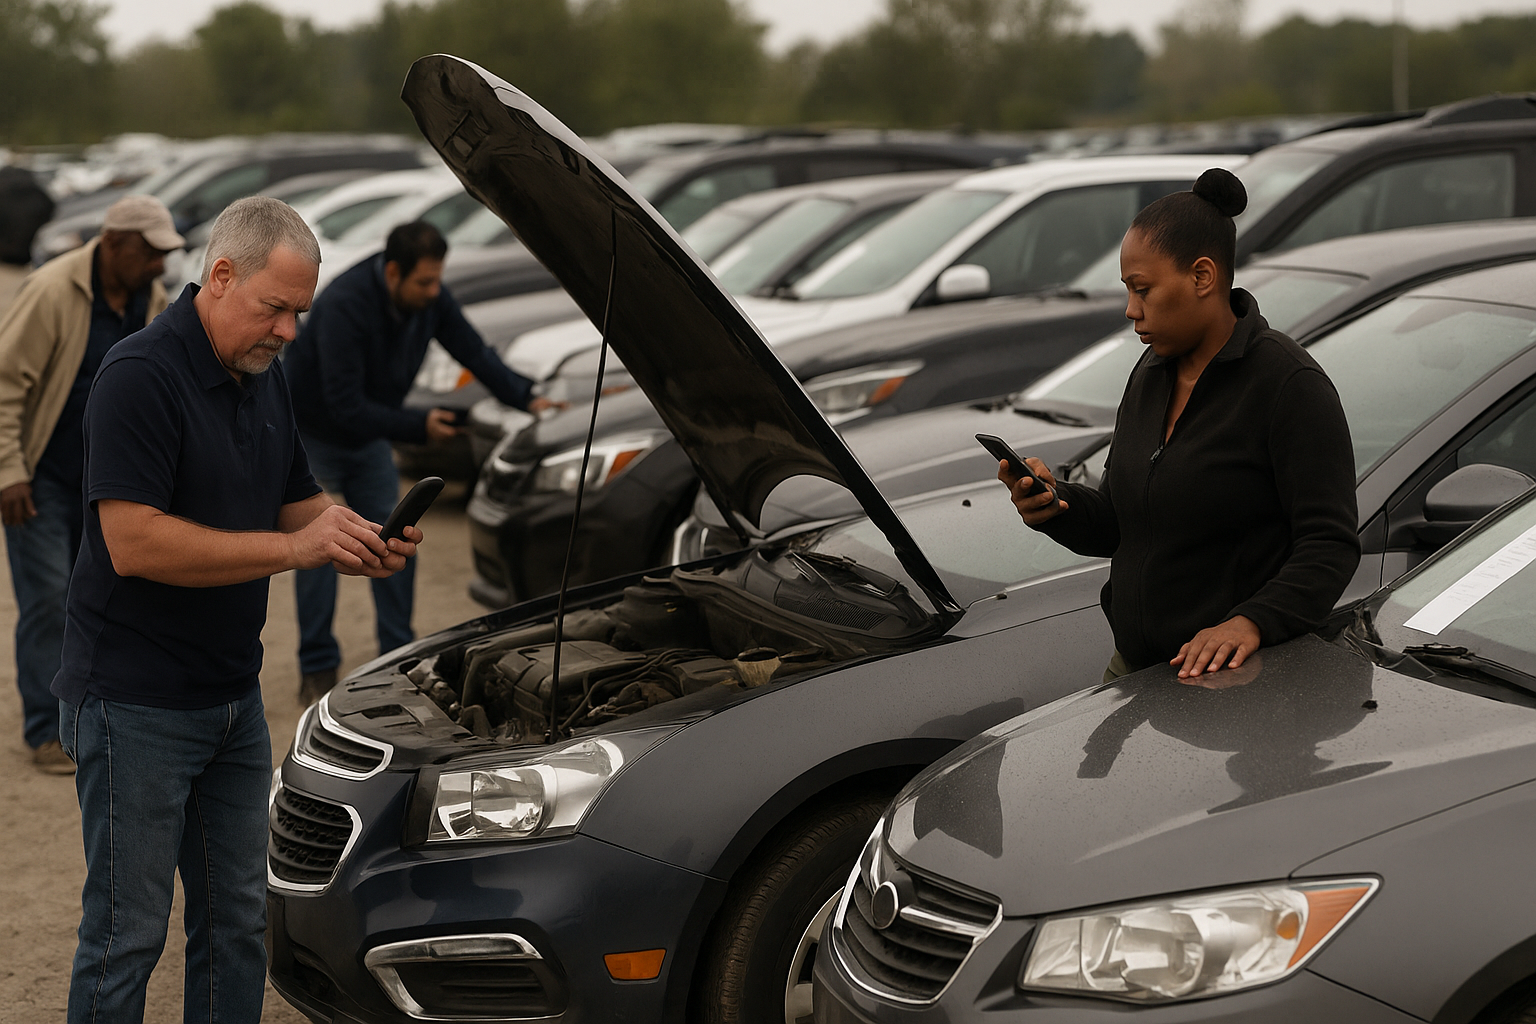
A car does not become valuable only when it arrives at an auction. Value gets decided when somebody understands its condition, demand, repair economics, transport cost and best available buyer. The party with the best information at that moment has the advantage.
Copart has just written a $1.9 billion cheque to own more of that moment.
The price tells you what Copart really wants
The offer is a 45% premium to ACV’s unaffected closing price on August 10, before reports of a possible transaction surfaced. It is also a 41% premium to ACV’s 30-day volume-weighted average price through September 9.
That is not a bargain-bin purchase. Copart wants this badly enough to end the conversation with cash.
ACV reported $214 million in second-quarter revenue, up 10% year on year, and reaffirmed full-year 2026 revenue guidance of $845 million to $855 million. Its full-year adjusted EBITDA guidance was $73 million to $77 million, while its GAAP guidance still called for a net loss of $49 million to $44 million.
So Copart is not buying a neat little cash machine. On the midpoint of ACV’s revenue guide, the deal values the business at roughly 2.2 times annual revenue. On midpoint adjusted EBITDA, it is about 25 times.
That sounds punchy because it is punchy.
But it makes sense if Copart believes ACV’s standalone earnings are the wrong way to value the asset. ACV’s real appeal is its dealer relationships, national inspection capability, vehicle-condition data, marketplace workflow and tools such as ACV MAX, ClearCar, VIPER and True360. Those inputs can improve pricing, conversion and trust across a much larger network.
That is where an acquirer with scale can see value that public-market investors often cannot. Standalone, ACV had to keep investing to grow. Inside Copart, its data and workflow can be pushed through a much bigger operating system.
I have seen this in business repeatedly: the best acquisitions do not look cheap against last year’s profit. They look cheap against the profit that becomes possible once a stronger owner removes friction and feeds the asset distribution.
Of course, plenty of CEOs use that line to justify overpaying. The difference is whether the buyer actually owns the distribution, customer access and operating discipline to make it true. Copart has a credible case.
What has to be true for $1.9 billion to make sense
This deal does not work merely because Copart and ACV both touch cars. That is banker logic. The value depends on whether ACV’s inspection, valuation and marketplace workflow remain trusted by dealers while becoming more useful inside Copart’s broader network.
Copart needs more than a bigger customer list. It needs better decisions: stronger pricing, faster conversion, more accurate routing and better matching between each vehicle and the buyer most likely to pay up.
That is why the first full year being neutral to earnings matters less than it sounds. Copart has said it expects near-term cost and revenue synergies, with the acquisition neutral to earnings in the first full year and accretive from fiscal 2028 onward. The real test is whether the combined business produces better transaction economics without damaging the dealer trust that made ACV valuable in the first place.
If it does, the premium will look less like an expensive auction purchase and more like the cost of buying a decision engine that would take years to build.
If it does not, Copart has paid a serious price for adjacency.
Copart is buying growth because its core business has slowed
Here is the bit management would rather you not skim past.
For the financial year ended July 31, Copart generated $4.7 billion in revenue and $1.5 billion in net income. Those are excellent numbers. But revenue grew just 0.4% for the year, while net income fell 4.4%. In the fourth quarter, revenue grew 2.4%, gross profit fell 5.5%, and net income fell 17.4%.
Nothing is broken. But a high-quality mature business with slowing growth has two choices: accept a lower growth profile, or intelligently expand the surface area where it can win.
Copart has chosen expansion.
The smart part is that ACV is adjacent without being identical. Copart is not wandering into a random software category because some banker produced a colourful deck. It is stepping into dealer-to-dealer wholesale, where its existing buyer network, physical footprint and transport capability can matter.
ACV gets a parent with scale. Copart gets a new source of vehicle volume and a thicker layer of data around each vehicle. Dealers may get more liquidity and better buyer reach. That is the optimistic case.
The less optimistic case is that wholesale dealers do not want a dominant salvage-auction operator becoming more central to their trade-in and inventory decisions. In marketplaces, participants care about price, yes, but they care just as much about neutrality and trust. If dealers believe the platform is steering economics too aggressively toward the parent, they will find another route.
That is why keeping ACV as an independent subsidiary under its existing leadership is not a fluffy post-deal courtesy. It is commercially necessary.
The overlooked asset is trust in the inspection
Most people will call this a digital-auction deal. I think that misses the important bit.
The asset is trusted condition data.
Used-car wholesale is a confidence game with real consequences. A dealer bidding remotely needs to know whether the car has hidden damage, poor paintwork, mechanical issues, tyre problems or an interior that looks like it hosted a small riot. The faster and more reliably a marketplace turns that uncertainty into a usable condition report, the more transactions it can make happen.
ACV’s inspection and valuation tools do that job. Copart’s vast transaction history and global buyer base can make the resulting market more liquid. Liquidity attracts sellers. Sellers attract buyers. Buyers improve price discovery. Better price discovery creates more trust.
That flywheel is why marketplace businesses can become monsters once they get enough density.
And this is the contrarian point: the deal may be less about cost synergies than about data compounding. Copart has said it expects near-term cost and revenue synergies, with the acquisition neutral to earnings in the first full year and accretive from fiscal 2028 onward. Fine. Cost cuts are nice. Cross-selling is nice.
But the bigger prize is a combined dataset that helps determine what a vehicle is, what it is worth, where it should go and who is most likely to pay up. That is not a quarterly synergy line. That is the basis for better economics for years.
Cash is a strategic weapon, not a trophy
Copart will fund the deal with cash on hand. There is no financing condition, and both boards have approved the transaction. The companies expect to close by the end of calendar 2026, subject to the tender offer, Hart-Scott-Rodino clearance and customary conditions.
That matters.
When a market gets uncertain, founders and executives often become obsessed with preserving cash so they can feel safe. Fair enough. But cash sitting idle beyond what the business genuinely needs is not safety; it is an option. Its job is to let you buy when an asset is strategically available and competitors are slower, poorer or more timid.
Copart’s move says it sees the next decade of vehicle remarketing as more digital, more data-driven and more integrated. It is using a strong balance sheet to shape that future rather than waiting to be disrupted by it.
That is how disciplined companies stay relevant. They do not chase every shiny thing. They buy the bottleneck.
What this means for you
If you are a founder, stop asking whether your business has “AI potential.” That phrase has become corporate wallpaper.
Ask three sharper questions instead:
1. Where does my customer make an irreversible decision? In ACV’s world, it is the moment a dealer prices, buys or disposes of a vehicle. Find your equivalent. That is where valuable workflow lives.
2. What data gets created there that nobody else can easily recreate? Not vanity dashboard rubbish. I mean data attached to actual economic behaviour: condition, price, conversion, loss, demand, failure, repeat purchase.
3. Can I become the trusted system of record before I try to become the marketplace? Trust first. Liquidity second. Margin third. Get that order wrong and you build a very expensive toy.
If you are an investor, do not only hunt for companies with fast revenue growth. Look for businesses sitting in the flow of high-value decisions, especially when their data gets more useful with every transaction. Those businesses can be worth much more to a strategic buyer than their current profit statement suggests.
And if you are an operator with cash, remember this: preserving optionality is not the same as refusing to act. Copart’s $1.9 billion ACV deal is a reminder that the best time to deploy capital is often when you can buy a capability that would take a decade to build properly.
You do not need to own every part of your customer’s journey. But if someone else owns the decision point where value gets set, they will eventually own more of your margin too.