James Dolan’s $13.5B Knicks-Rangers Split Is a Lesson in Trapped Value
A $3.65 billion hockey team is being spun out because Wall Street was effectively getting it for free. That is what happens when a great asset is buried inside a messy structure.
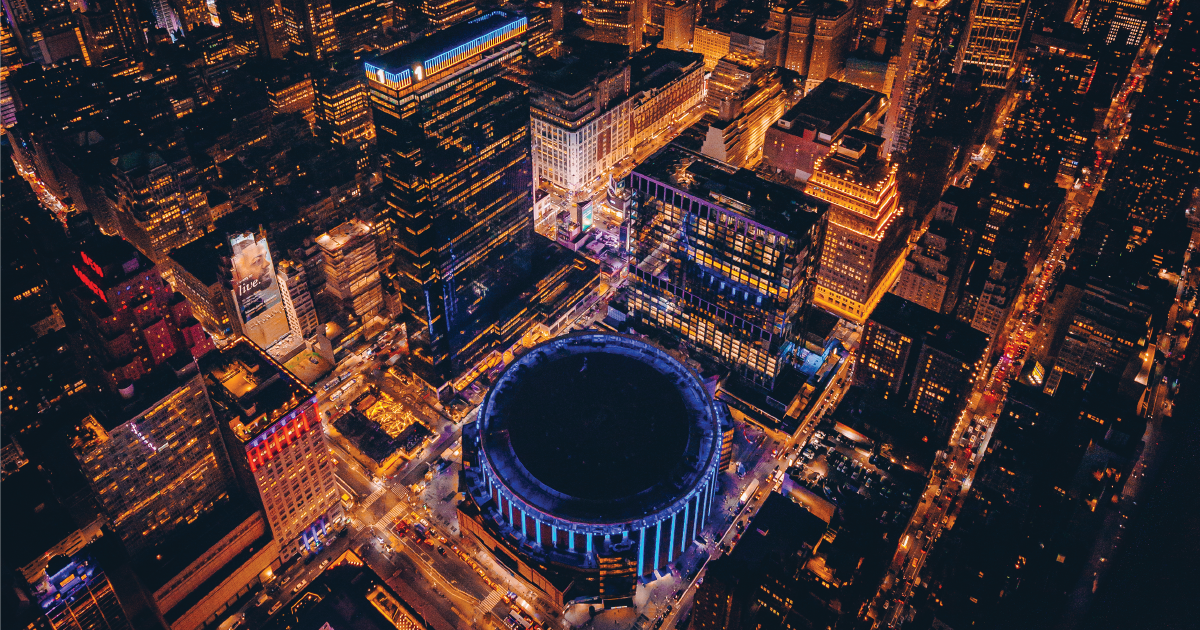
The New York Rangers are worth an estimated $3.65 billion, yet investors in Madison Square Garden Sports were effectively being offered them as a free side dish.
That is not a hockey problem. It is a business-structure problem — and James Dolan is now trying to fix it by splitting a combined $13.5 billion sports empire into two public companies. ([sports.yahoo.com](https://sports.yahoo.com/articles/knicks-rangers-split-explaining-msg-181158720.html?utm_source=openai))
The core story: James Dolan is breaking up the bundle
On August 14, Madison Square Garden Sports publicly filed the Form 10 registration statement for its proposed Rangers spin-off. The plan is simple on paper: the existing MSG Sports business becomes MSG Knickerbockers Corp., holding the New York Knicks and Westchester Knicks; the new company becomes MSG Rangers Corp., holding the New York Rangers, Hartford Wolf Pack and MSG Training Center. Current MSG Sports shareholders would receive a pro-rata distribution of 100% of the new Rangers company’s stock in a tax-free spin-off, if the transaction closes. ([msgsports.com](https://www.msgsports.com/msg-sports-publicly-files-form-10-registration-statement-for-proposed-spin-off-of-rangers-business-from-knicks-business/))
MSG Sports says it expects completion by the end of October 2026, subject to board approval, league approvals and the tax work being signed off. That is corporate speak for: it is moving, but don’t book the victory parade just yet. ([msgsports.com](https://www.msgsports.com/msg-sports-publicly-files-form-10-registration-statement-for-proposed-spin-off-of-rangers-business-from-knicks-business/))
The timing is not subtle. Jalen Brunson just led the Knicks to the 2026 NBA championship, ending a 53-year title drought; he dropped 45 points in the Game 5 clincher against the San Antonio Spurs and won Finals MVP. Mikal Bridges, Josh Hart and Karl-Anthony Towns helped turn a valuable franchise into an even louder global asset. ([nba.com](https://www.nba.com/news/jalen-brunson-wins-bill-russell-trophy-as-2026-nba-finals-mvp?utm_source=openai))
Sportico’s latest figures put the Knicks at $9.85 billion and the Rangers at $3.65 billion. Against that combined $13.5 billion estimate, MSG Sports had an enterprise value of roughly $9.6 billion — a 29% gap. That’s the sort of discount that makes activist investors start clearing their throats and investment bankers start ordering better wine. ([sports.yahoo.com](https://sports.yahoo.com/articles/knicks-rangers-split-explaining-msg-181158720.html?utm_source=openai))
A championship is nice. Clean capital markets are nicer.
People get this backwards. They see the spin-off and assume Dolan woke up one morning feeling generous toward minority shareholders.
Maybe. But this is mainly the cold logic of asset separation.
The Knicks and Rangers share a famous address, overlapping commercial machinery and one controlling family. But they are not the same investment. The Knicks sit in the NBA, with its new national media-rights deals already lifting MSG Sports’ league-distribution revenue. The Rangers sit in the NHL, a different league with a different media outlook, different salary economics and a different pool of buyers if Dolan ever wants to sell a minority interest or raise capital. ([msgsports.com](https://www.msgsports.com/madison-square-garden-sports-corp-reports-fiscal-2026-fourth-quarter-and-full-year-results/))
Bundling them forces investors to buy both at once. Want exposure to the NBA’s biggest market after Brunson’s title run? Bad luck — you also own a hockey club. Think the Rangers have standalone upside? You still have to buy the Knicks at whatever the market decides the bundle deserves.
That is how good assets get priced like a mediocre conglomerate: not because the assets are rubbish, but because the wrapper is inconvenient.
MSG Sports’ own fiscal 2026 results make the point. The company reported $1.1538 billion in annual revenue, up 11%, yet operating income was only $28.9 million. The two teams also delivered higher average per-game revenue across tickets, suites, sponsorship, food, beverage and merchandise. ([msgsports.com](https://www.msgsports.com/madison-square-garden-sports-corp-reports-fiscal-2026-fourth-quarter-and-full-year-results/))
That apparent mismatch — enormous franchise values, strong revenue growth, skinny reported operating profit — is exactly why sports ownership can confuse ordinary investors. A team is not valued like a plumbing wholesaler. Buyers are paying for scarcity, league membership, media rights, prestige, future revenue growth and, frankly, the chance to own something nobody can build from scratch.
There are only 30 NBA teams. You cannot download a rival New York Knicks from the App Store.
The overlooked complication: the Rangers are not leaving Madison Square Garden
Here is the bit investors should not ignore while they admire the headline valuation.
The Rangers spin-off does not magically sever the commercial knots tying the teams to the broader Dolan universe. Madison Square Garden Entertainment owns and operates the arena. The Knicks and Rangers have long-term arena licence agreements running through June 30, 2055. Those arrangements cover far more than simply unlocking the doors on game night: suite and club income is shared, MSG Entertainment manages food and beverage operations, takes a commission on in-arena merchandise, sells certain sponsorship inventory and provides game-day services. ([sec.gov](https://www.sec.gov/Archives/edgar/data/1636519/000163651925000027/msgs-20250630.htm))
That matters because a clean equity chart does not automatically produce a clean business.
In the fiscal 2025 filing, MSG Sports disclosed that the Knicks and Rangers receive 35% and 32.5%, respectively, of suite and club licence revenue collected by MSG Entertainment; each receives 50% of net food-and-beverage profit during its games; and the teams pay MSG Entertainment a 30% commission on merchandise sold at the Garden. The arena licences were structured with annual 3% escalators. ([s23.q4cdn.com](https://s23.q4cdn.com/716592820/files/doc_financials/2025/ar/MSGS-FY2025-Form-10K.pdf))
None of that makes the spin-off bad. It just means the deal is not a magic trick.
A separate Rangers ticker may make valuation easier to see. It does not remove related-party arrangements, nor does it remove the hard work of proving the Rangers can stand alone as an investable business rather than a premium sports asset with a complicated family tree.
That is the contrarian point: separation creates visibility, not necessarily value. Value only arrives if the new visibility changes what a buyer, lender or public-market investor is prepared to pay.
The real signal is Quentin Dolan, not the paperwork
The most interesting detail may not be the Form 10 at all.
In July, James Dolan named his son, Quentin Dolan, president, chief operating officer and alternate governor of the Rangers. James said he would step back from day-to-day Rangers responsibilities, while Quentin would work with president and general manager Chris Drury on team direction and strategy. Drury remains responsible for hockey operations and decision-making. ([msgsports.com](https://www.msgsports.com/quentin-dolan-named-president-chief-operating-officer-and-alternate-governor-of-the-new-york-rangers/))
Read that for what it is: governance succession is now being made visible alongside financial separation.
James Dolan is expected to remain executive chairman and CEO of both the Knicks and Rangers companies after the spin-off. So this is not an exit. It is not a sale. It is not a handover with a bow on it. But it gives the Rangers a clearer management spine and creates a vehicle that is easier to finance, value, partially sell or eventually hand down.
That optionality is worth a lot.
Most founders are too sentimental about structure. They keep every business inside one holding company because that is how they built it. Then they act surprised when investors slap a complexity discount on the whole lot.
The lesson is blunt: your ownership chart should serve your next move, not commemorate your past.
What this means for you
You probably do not own the Knicks, the Rangers or a $13.5 billion sports portfolio. Join the club.
But you may own — or be building — a business with the same issue: one excellent asset trapped inside a structure that makes it difficult to value, fund, sell or understand.
Do three things this week.
First, identify your hidden discount. If someone bought your business tomorrow, what would they struggle to separate? A profitable product line buried inside a services business? Valuable IP mixed with low-margin operations? A property asset obscured by trading-company accounts? Write it down.
Second, separate reporting before you separate entities. Give each meaningful business line its own revenue, gross margin, customer concentration, working-capital needs and management accountability. If you cannot explain an asset’s economics on one page, no investor will pay top dollar for it.
Third, distinguish visibility from value. A restructure is not strategy. Spinning out a division does not improve its product, talent or customers. It merely makes the truth harder to hide. Do the operational work first; then use structure to make the upside investable.
Dolan’s move is a useful reminder that even billion-dollar franchises can be mispriced when the ownership structure is a dog’s breakfast. The market does not pay extra because you own good things. It pays extra when it can see them clearly, trust the economics and believe there is a clean path to cashing in.
That is a lesson worth more than a championship ring.