JLL’s $71.8B Property Surge Says Prime Offices Aren’t Dead
Commercial property didn’t die. Cheap, forgettable property died. JLL’s $71.8 billion cross-border surge shows serious money is buying quality while everyone else is still telling ghost-town office stories.
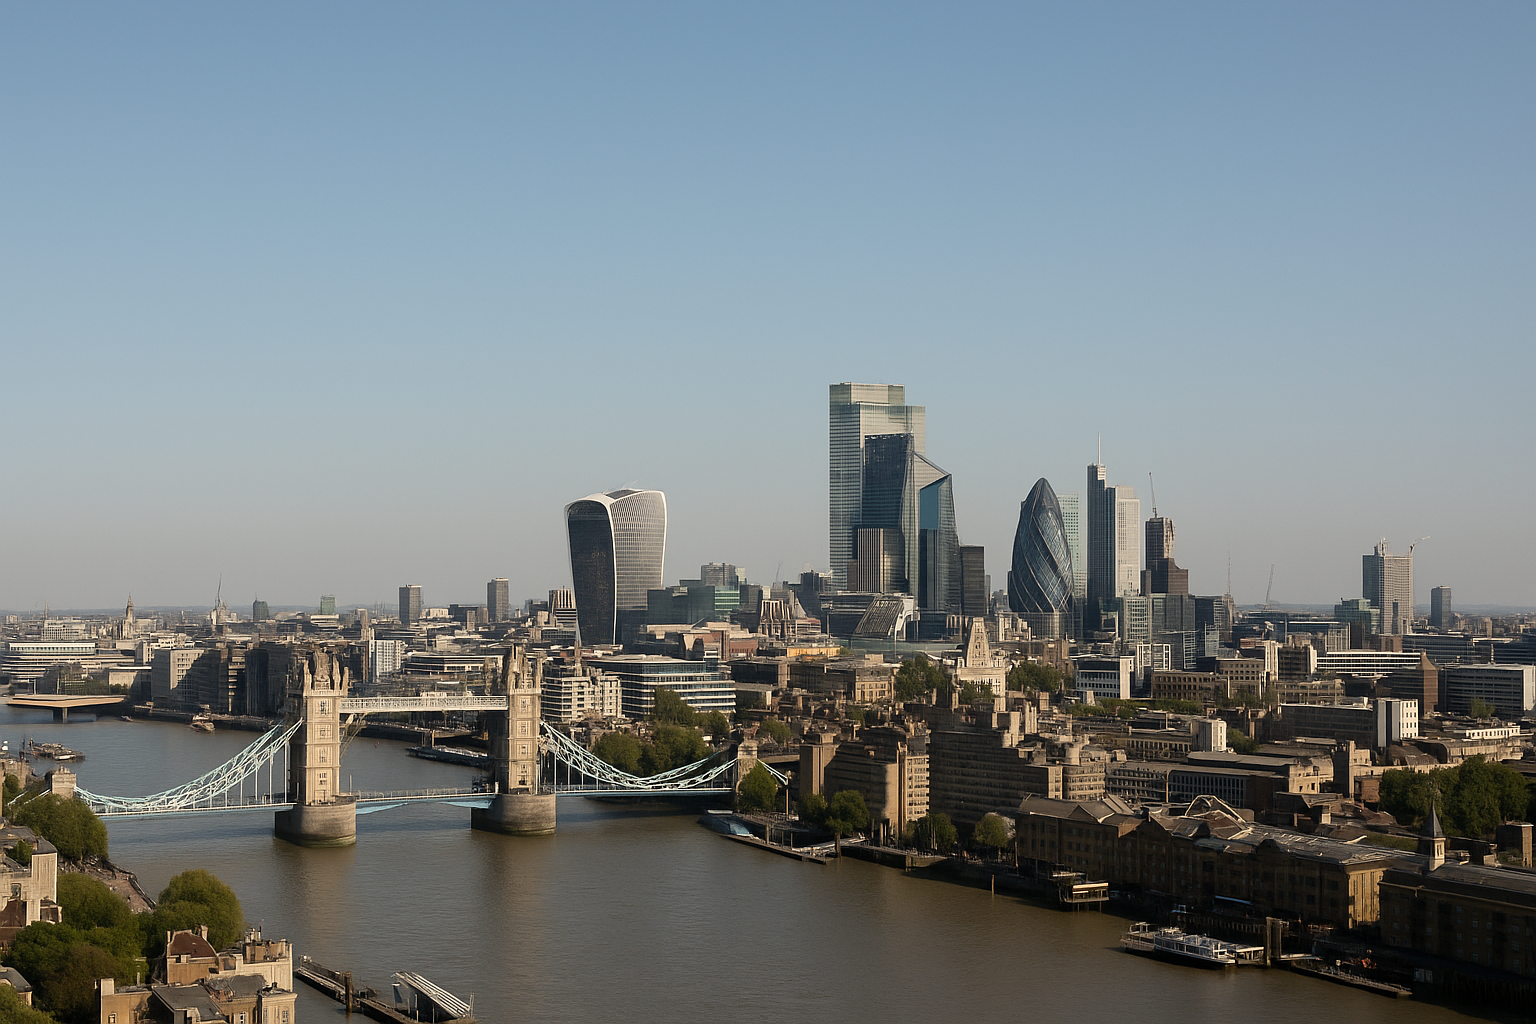
Commercial property didn’t die. Cheap, forgettable property died.
JLL says cross-border commercial-property investment jumped 56% to $71.8 billion in the first half of 2026. And a decent chunk of that money went into premium offices. So much for the lazy prediction that every office building would become an overpriced indoor car park.
That does not mean property is back to normal. It means capital is doing what capital always does when the market gets ugly: ignoring the broad label and hunting for assets where the downside has already been punched in the face.
That distinction matters enormously. If you’re still treating “commercial real estate” as one investment category, you’re not investing. You’re reading headlines.
JLL’s $71.8 billion number is a vote for scarcity, not a vote for everything
The big story is not merely that international money returned to property. It is where it returned.
According to JLL data reported by Reuters on September 18, cross-border investment in commercial property rose 56% year-on-year to $71.8 billion in the first half. Total building transactions rose only 10%, to $604.6 billion, according to separate MSCI data.
Read that again. Foreign capital grew far faster than the overall market.
That tells you the buyers with the most choice are not spraying money across every shabby building with a leasing brochure. They are concentrating it. They are looking for assets that can justify institutional ownership: strong locations, quality tenants, durable demand, good transport, genuine scarcity and a realistic path to refinancing.
Asia saw international property investment jump fourfold to $19.3 billion. Europe rose 31% to $39.9 billion. Singapore was the leading global destination, with $8.7 billion in cross-border volume. Reuters also reported that international investors were active in major European cities including London and Milan, with a re-emergence of demand for office property.
That is not a broad recovery. It is a sorting machine.
The best properties are getting repriced as assets. The average ones are still getting repriced as problems.
There’s a brutal lesson in that for property investors: location remains important, but “location” is now shorthand for a much tougher list. Is the building useful? Is it efficient? Can it attract people five days a week if required? Is it near customers, staff and transport? Is there enough supply coming behind it to crush rents? Does it require a heroic refinancing story to work?
If the answer to those questions is vague, the building is not cheap. It is simply carrying risks the seller would rather you discover after settlement.
The office comeback is real — but don’t get carried away
The fashionable position for years has been that offices are finished because hybrid work won. That was always too neat.
Hybrid work changed demand. It did not abolish the need for offices. Companies still need places to train younger staff, sell, collaborate, make decisions, recruit, manage difficult work and build a culture that does not feel like a Slack channel with payroll.
But here’s the catch: workers and employers do not want just any office.
The comeback Reuters identified is in premium offices, particularly in major cities. That’s an important adjective people conveniently leave out when they start declaring a sector reborn. A top-grade building in a deep employment market is not the same investment as a tired suburban block with poor access, old lifts, expensive energy use and vacancies hidden behind rent-free periods.
The market is becoming more polarised. The best assets can command attention because tenants are consolidating into better space. The worst assets can lose tenants and still have bills, debt and capital-expenditure requirements that do not care about anyone’s work-from-home policy.
This is the bit many small investors miss. They hear “offices are back” and assume the opportunity is to buy whatever is down 40%. That is how people end up owning a bargain with no buyers, no tenants and no lender enthusiasm.
A falling price is not an investment thesis. It is a question mark.
Debt is still the adult in the room
The timing is awkward because property is wildly sensitive to borrowing costs, and borrowing costs are not behaving.
In the US, Freddie Mac reported that the average 30-year fixed mortgage rate rose to 6.95% for the week ending September 17, up from 6.76% a week earlier — the highest level since January 2025. Fortune’s September 18 rate data put the average 30-year conventional mortgage rate at 7.065%.
Those are residential figures, but the message travels straight into commercial property: capital is expensive, refinancing is harder, and buyers cannot pretend yesterday’s debt assumptions still work.
Reuters reported that JLL expects rising borrowing costs to weigh on commercial-property activity in the second half of 2026. That should not surprise anyone. Property values are not set by optimism. They are set by the relationship between income, risk and the cost of money.
When debt gets dearer, a buyer has only a few levers:
- pay less for the asset; - accept a lower return; - put in more equity; - find higher rents or lower costs; or - walk away.
The fourth option is the one people abuse. You cannot model a rent increase because it would be convenient. You need a reason tenants will actually pay it. You cannot assume a cheap refinance because some bloke on YouTube says central banks will cut rates. You need to know what happens if rates stay annoying for longer than your spreadsheet can emotionally handle.
The investors winning in this market are not necessarily predicting rates perfectly. They are buying assets that survive being wrong.
The overlooked angle: cross-border money is often smarter money
There is a temptation to view foreign capital as dumb money — distant buyers with too much cash and not enough local knowledge. Sometimes that is true. Plenty of overseas investors have overpaid for trophy assets because they wanted a postcode to put in an annual report.
But the current numbers suggest a different dynamic.
Cross-border buyers are not moving because property has become easy. They are moving because dislocation creates opportunity, and global capital can compare markets. A buyer looking at London, Milan, Singapore, Sydney and New York is not trapped by local sentiment. They can see relative value, currency movements, tenant demand, financing terms and supply conditions across markets.
That gives them an advantage over the local investor who owns one building, knows every crack in its car park and becomes emotionally attached to a price from 2021.
The lesson is not that international buyers are always right. The lesson is that they tend to be more ruthless about allocation. If one market’s risk-adjusted return is rubbish, they can go somewhere else.
Most individual property investors cannot buy an office tower in Milan. Fair enough. But you can steal the mindset.
Stop asking, “Do I like property?” Ask, “Is this specific asset better than my other uses of capital after debt, tax, vacancy, repairs and my own time?”
That is a much less romantic question. It is also the one that makes money.
What this means for you
First, do not confuse a sector headline with permission to buy. JLL’s $71.8 billion cross-border surge is evidence that quality commercial property is attracting capital. It is not evidence that your local vacant retail strip is suddenly a genius purchase.
Second, underwrite debt like a pessimist. If you are buying property, model a refinance rate that is higher than today’s, a vacancy period longer than you want, and repairs that cost more than the agent mentioned. If the deal still works, you may have something. If it only works with perfect rents and falling rates, you do not own an investment. You own hope with council rates.
Third, look for the gap between “bad category” and “good asset.” That is where markets get lazy. A premium office in a strong city, a well-located industrial asset, or housing where supply is genuinely constrained can be mispriced when investors sell the whole category in disgust. Conversely, a poor asset in a fashionable category can still be a disaster.
Fourth, make liquidity part of the investment case. Who buys this from you in five years? Who lends against it? Who rents it if your current tenant leaves? If your answer relies on “someone will want it,” keep your cheque book shut.
Finally, remember what this market is really saying: money has not abandoned property. It has become selective.
That is uncomfortable if you own mediocre assets. It is useful if you are patient, cashed up and willing to do the work most people skip. In property, the crowd loves a simple story. The serious money is usually making a more specific bet.