nVent’s $1.75B Maverick Deal: Data-Centre Power Is the Real Toll Booth
nVent is paying $1.75 billion for data-centre power because without it, an AI data centre is just an air-conditioned shed full of delayed invoices.
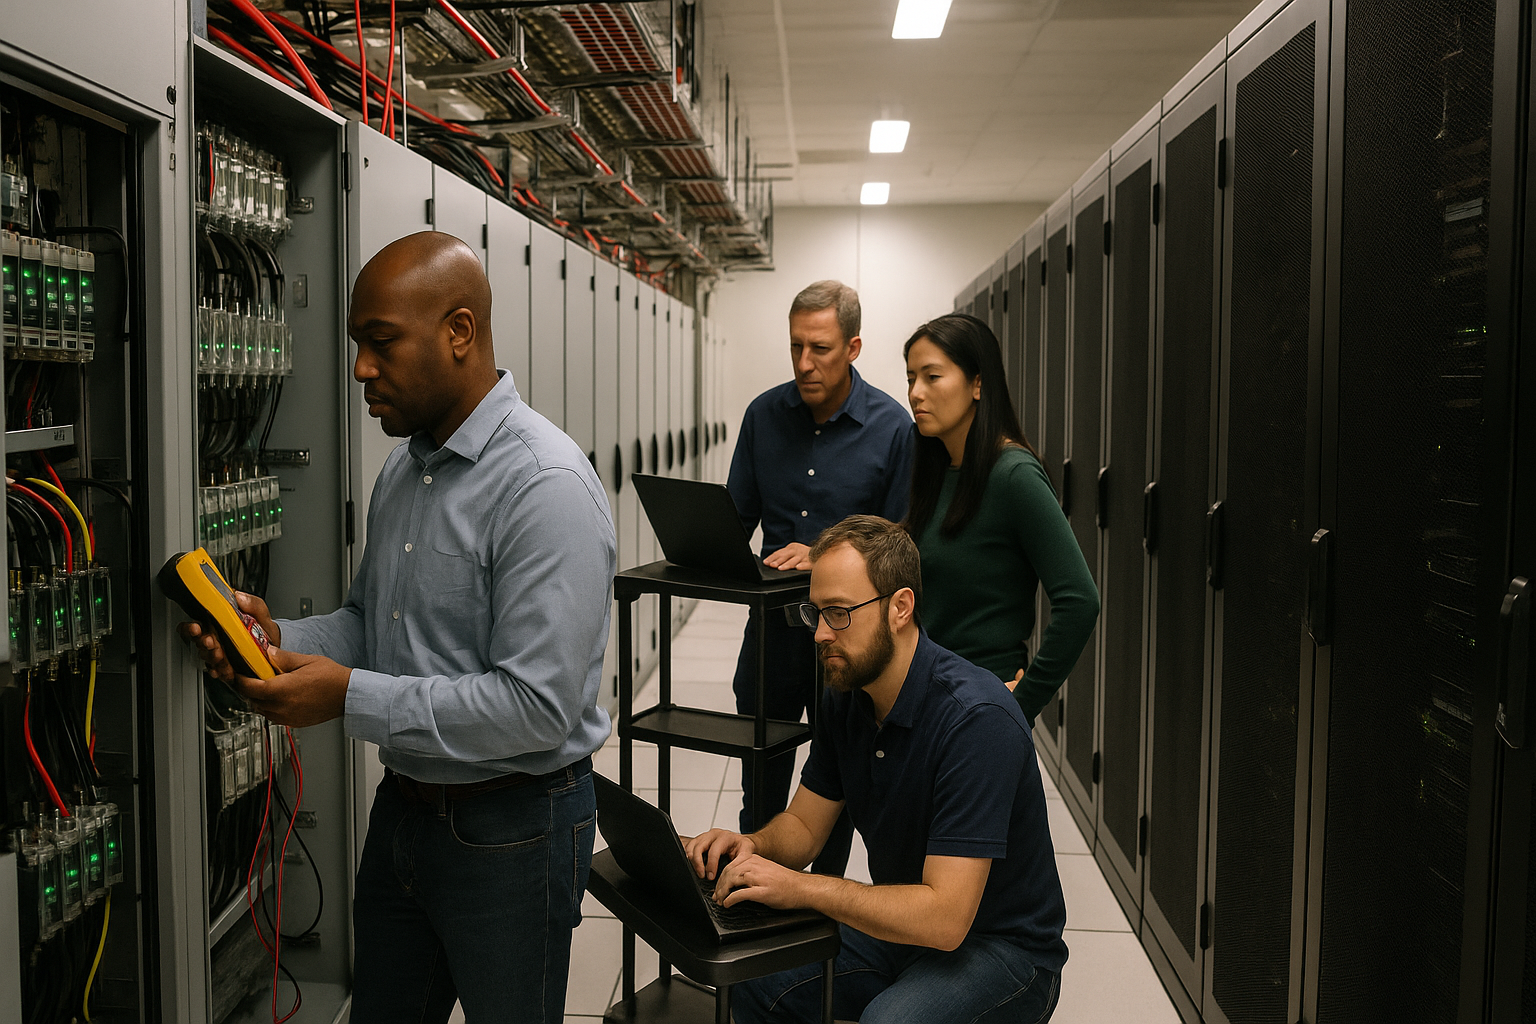
nVent is paying $1.75 billion because a data centre without power distribution is not an AI factory. It is an air-conditioned shed full of delayed invoices.
That is not a bet on artificial intelligence. It is a bet that the people promising AI cannot build enough data centres without buying very expensive electrical gear first.
And frankly, that is where the real money has been hiding.
Everyone wants to own the model, the chip or the flashy software layer. Fair enough. They make better headlines. But a data centre without switchgear, switchboards, modular power systems and people who know how to install the lot is just an air-conditioned shed full of delayed invoices.
On August 24, nVent announced a definitive agreement to acquire Texas-based Maverick Power for $1.75 billion, subject to customary adjustments. The deal includes up to $550 million more in cash if Maverick hits performance metrics in 2027 and 2028. nVent expects Maverick to generate about $700 million in 2026 revenue, and says the business has roughly 900 employees across Texas and Arizona.
That puts the base price at about 11.5 times anticipated 2026 adjusted EBITDA, or roughly 10.5 times after the present value of expected tax benefits. It is not cheap if you think Maverick is merely a manufacturer of metal boxes. It is more understandable if you recognise it as a scarce execution platform plugged directly into the data-centre buildout.
This is a deal for the bottleneck, not the buzzword
Maverick makes the unsexy kit that turns incoming electricity into usable, controlled power inside mission-critical facilities: low- and medium-voltage switchgear, switchboards, modular systems and related services.
In plain English: this is the infrastructure that stops a data centre becoming a very large, very expensive blackout.
That matters because the AI race has created a supply-chain problem far beyond GPUs. There are not enough sites with enough grid connection. There are not enough transformers. There are not enough skilled electrical contractors. There is not enough switchgear capacity. And there are definitely not enough suppliers that can engineer, build and deliver integrated systems quickly enough for hyperscalers, developers and enterprise customers who are all trying to get online yesterday.
Maverick had already been acting like a business that knew the window was open. In May, it announced more than 1 million square feet of additional manufacturing capacity in North Texas, designed to support demand from data centres, industrial operators and other critical-infrastructure customers. It said those facilities were expected to create 2,000 new jobs across engineering, manufacturing and operations.
That is the bit worth paying attention to. The asset is not merely Maverick’s current revenue. It is its capacity, customer relationships, engineering capability and ability to get complex power systems out the door at speed.
You do not build that by hiring a few sales reps and putting “AI infrastructure” in a pitch deck.
nVent has been preparing for this punch
This deal did not come from nowhere. nVent has spent years reshaping itself into a more focused electrical-infrastructure company.
In January 2025, it sold its Thermal Management business to a Brookfield affiliate for $1.6 billion in net cash proceeds. Four months later, it completed the roughly $1 billion acquisition of Avail Infrastructure Solutions’ Electrical Products Group — a business covering enclosures, switchgear and bus systems used in power utilities and data centres.
Now it is back at the table with Maverick.
That sequence matters. Sell a non-core business. Buy closer to the infrastructure bottleneck. Then buy deeper into the same value chain. That is portfolio surgery, not random corporate shopping.
nVent’s own numbers show why management is leaning in. Its Systems Protection segment — the business serving mission-critical applications including data centres — reported second-quarter 2026 sales of $1.07 billion, up 69.6% year on year. The company said organic growth in infrastructure was the principal driver, including growth in data centres. Segment income rose 81% to $248.2 million.
When you are seeing that sort of demand in the part of the business you actually want to own, sitting on your hands in the name of “discipline” can be its own form of stupidity.
The key is whether you buy an asset that extends your advantage or simply lets you tell a more exciting story on the earnings call. Maverick appears to do the former. It gives nVent a broader power-distribution platform alongside its existing protection, enclosure, cooling and electrical-connection products.
The pitch is simple: sell a more complete system to the same data-centre customer.
That is far better economics than selling one component, watching somebody else sell the next five, and hoping your purchasing manager gets invited back next year.
The $550 million earnout is the smartest part of the deal
The headline price is $1.75 billion. The more interesting figure is the potential $550 million in additional consideration.
nVent has structured that extra payment around Maverick achieving performance targets in 2027 and 2028. Good. That is how buyers should approach a hot market.
When demand is booming, sellers will always tell you the backlog is magnificent, the customers are desperate and next year’s growth is practically divine intervention. Sometimes they are right. Sometimes they are simply packaging a cyclical spike with a glossy presentation.
An earnout does not eliminate risk, but it means the seller has to keep delivering after the champagne has been drunk and the lawyers have sent their final invoice.
It also tells you something about the negotiation. nVent was willing to pay up for real performance, but it was not willing to write the entire future upside cheque today. That is disciplined aggression — a phrase corporate types love to butcher, but here it actually fits.
There is another useful signal in the financing. nVent plans to fund the acquisition with cash on hand and new debt, with Bank of America providing committed bridge financing. As of June 30, nVent reported $256 million of cash on hand, so debt is plainly doing meaningful work here.
That is not automatically a red flag. Good businesses use debt to buy productive assets all the time. But it raises the standard: Maverick has to convert its backlog and growth story into cash, not just revenue. The deal is expected to be accretive to adjusted earnings per share in the first full year after closing, which nVent expects in the fourth quarter of 2026. That is management’s promise. The conversion of orders into profitable delivery is the test.
The overlooked risk: everybody is chasing the same shovel
Here is the part the market may underappreciate: AI infrastructure is becoming crowded trade territory.
Every industrial company with a cable, cooling unit, transformer, generator, enclosure or electrical-service crew is now being valued through the AI lens. Some deserve it. Others have discovered a new adjective for the same old business.
Maverick looks more credible than most because it is directly tied to engineered power distribution and has been adding capacity. Still, nVent is paying a growth multiple because growth is expected. If data-centre construction schedules slip, grid connections stall, capital spending tightens or customers consolidate suppliers more aggressively than expected, the multiple will look less clever in hindsight.
There is also execution risk. Maverick’s appeal is its responsiveness and engineering capability. Big companies often buy entrepreneurial operators and then suffocate them under meetings, procurement rules and “synergy workstreams”. That would be a spectacular own goal.
The buyer needs to add balance-sheet strength, customer reach and product breadth without ruining the speed that made the target valuable in the first place.
That is the whole game.
The contrarian angle: this is not an AI deal at all
Calling this an AI deal is convenient, but lazy.
It is really an electrification deal. AI is merely the loudest customer.
The same systems Maverick provides matter for industrial facilities, utilities and other mission-critical projects. Data centres are accelerating demand, but the deeper theme is that modern economies need far more power moved, protected, monitored and distributed than they used to.
That is a much sturdier thesis than betting on which AI model wins next month.
Founders should notice this because there is a lesson in where value accrues. The most attractive business is not always the one that gets attention. It is often the one sitting in the workflow where failure is intolerable, delivery is difficult and replacing the supplier is a complete pain in the arse.
That is Maverick’s neighbourhood.
What this means for you
If you are an operator, stop asking whether your business is “an AI company”. It is usually a pointless question. Ask where your customers are hitting a capacity constraint, a compliance constraint, a labour constraint or a delivery constraint — then build around that.
If you are a founder, look for the unglamorous part of a growth market that everybody else has underestimated. Revenue gets exciting when your product is required for the project to go live, not merely nice to have once it does.
If you are an investor, separate AI enthusiasm from infrastructure economics. The companies selling indispensable physical capacity can be excellent businesses, but only if their pricing power, backlog quality, delivery capability and balance sheet support the valuation. Do not buy a “picks and shovels” story without checking whether the shovel maker can actually manufacture shovels on time.
And if you are considering an acquisition, steal nVent’s best move here: pay properly for demonstrated performance, but do not hand over every dollar for forecasts. Tie a portion of the price to the future the seller is so confident about.
That is not being cheap. That is refusing to confuse excitement with cash flow — a mistake that has cost plenty of clever people far more than $550 million.