The Data Center Land Rush Has Hit a Hard Wall: Power, Property Rights and Politics
AI data centers are remaking real estate—but the scarce asset is no longer land. Georgia’s grid buildout shows why power access, easements and local consent now determine who wins.
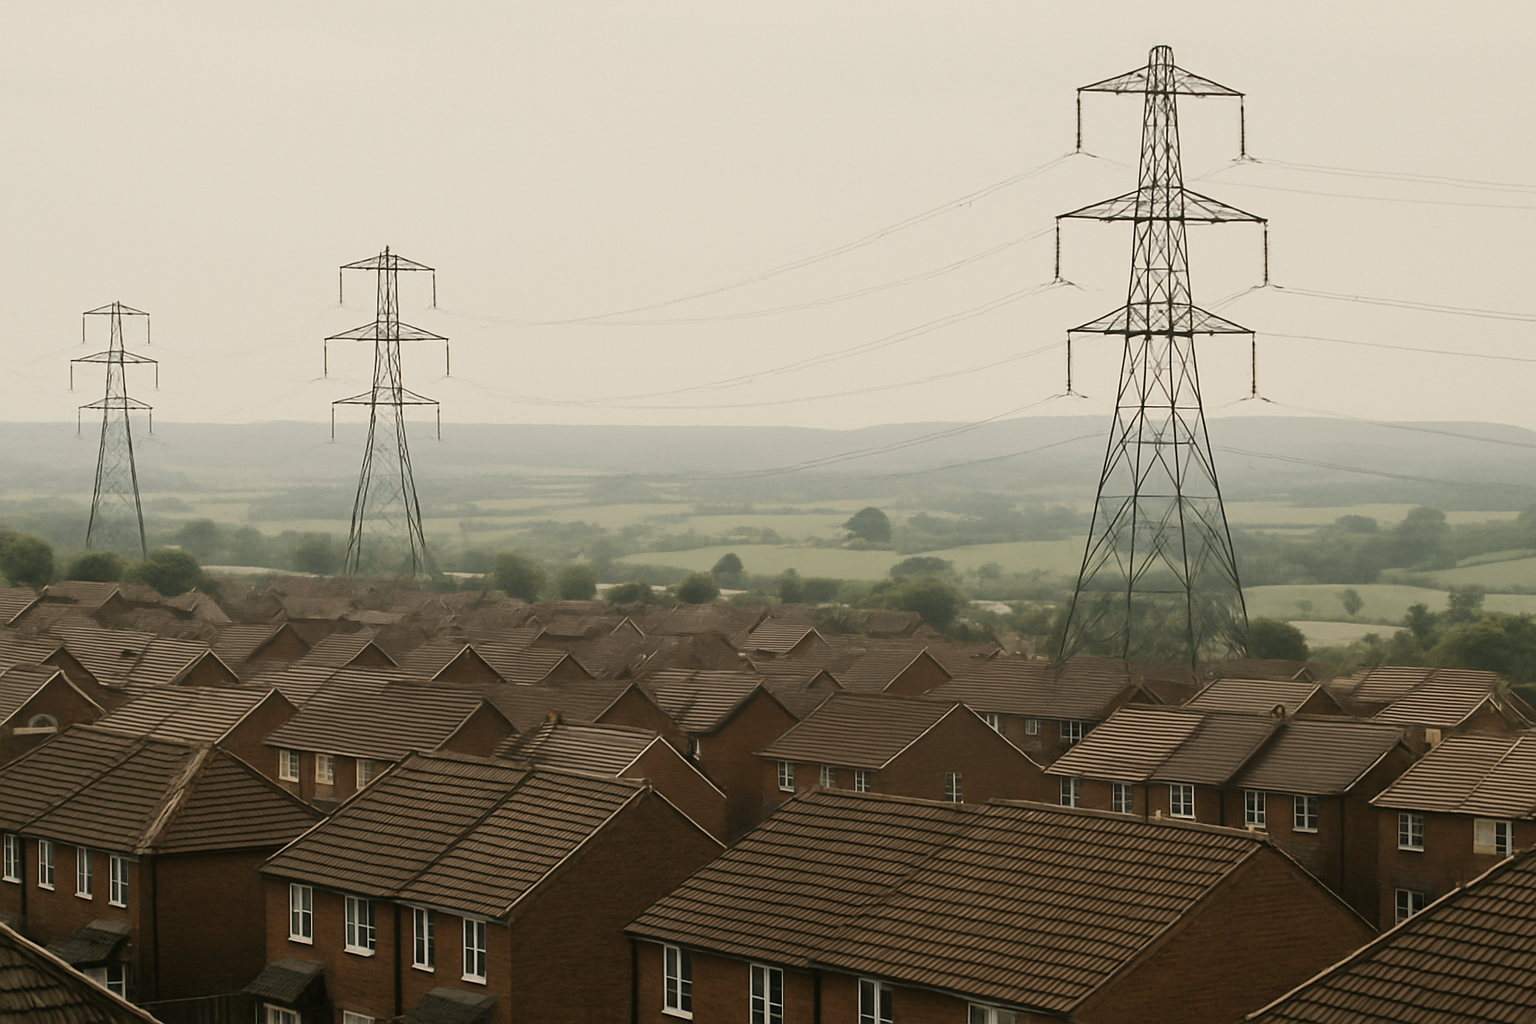
The real estate story is no longer the building
The most important property-market shift right now is hiding in plain sight: the AI data-center boom is no longer principally a race to buy land, develop shells, or sign hyperscale leases. It is becoming a contest for power corridors—and that changes the risk profile of real estate investment.
Georgia offers the clearest current example. Georgia Power is pursuing a grid-expansion program that includes more than 1,000 miles of transmission lines across more than 330 parcels and roughly 10 gigawatts of additional generation capacity over five years. One proposed 35-mile line, connecting the Ashley Park Substation to Plant Wansley, runs through Fayette, Heard, Fulton, and Coweta counties. It could require residential acquisitions, easements, or—in exceptional cases—eminent-domain action.
That may sound like a utility story. It is not. It is a real estate story because the map for power is rapidly becoming the map for land value.
For the past several years, investors treated data centers as perhaps the cleanest expression of the digital-infrastructure thesis: long leases, investment-grade tenants, powerful demand growth, and a seemingly inexhaustible need for computing capacity. The logic was straightforward. Find cheap land near fiber, build capacity, secure a tenant, and watch the asset class compound.
That formula is now incomplete. The crucial question is not whether a site can physically host a data center. It is whether the local grid can serve it, on what timeline, at what cost, and with what political blowback.
Georgia shows the next phase of the AI-property trade
Georgia has become a major data-center destination. The state has more than 200 operating data centers, with nearly 170 in the Atlanta area, according to recent reporting. Its appeal is familiar to developers: available land, connectivity, a business-friendly regulatory posture, and tax incentives that can exempt qualifying data-center equipment and infrastructure from state and local sales-and-use taxes.
Those incentives are meaningful. Projects generally must meet investment thresholds of $100 million to $250 million to qualify, depending on the program. For an owner, tenant, or capital partner, that can materially improve the economics of a development that already demands enormous upfront spending on electrical equipment, cooling systems, land preparation, and network infrastructure.
But incentives do not create electrons.
Georgia Power’s expansion program makes clear how quickly the bottleneck has moved upstream. The utility has said that its broader transmission plan is designed to meet the needs of a growing state and a growing base of large-load customers. A December 2025 agreement tied to the capacity plan indicated that approximately 80% of nearly 10,000 megawatts of planned generation was expected to power data centers.
That is the figure property investors should focus on. It is an admission that data centers are no longer simply another commercial use competing for industrial sites. They are reshaping regional infrastructure investment itself.
The traditional real estate-development sequence has been land, entitlement, construction, lease-up, and stabilization. For power-intensive assets, the new sequence is closer to power availability, interconnection, transmission upgrades, community acceptance, land control, and only then construction.
Put differently: a cheap parcel without power is not cheap. It is an option whose value depends on a utility timetable, regulatory approvals, and public tolerance.
The overlooked risk is not vacancy—it is the route
Data-center investors have spent years debating familiar underwriting variables: tenant credit, lease duration, construction cost inflation, server-density requirements, cooling technology, and the possibility that AI demand eventually disappoints.
Those are legitimate concerns. But the more underappreciated risk is linear infrastructure.
A data center can sit on a single parcel. The electricity required to support it may depend on a network of substations, generating assets, rights-of-way, and transmission lines that cross dozens or hundreds of separately owned properties.
That distinction matters because a developer can control a site. It cannot independently control the politics surrounding every mile of wire needed to energize that site.
In Georgia, the transmission program has already put homeowners and the utility on opposite sides of a property-rights dispute. Some owners along the proposed route have faced the prospect of selling or granting permanent utility easements. Georgia Power has said it begins negotiations at 125% of appraised value and uses eminent domain only as a last resort. Still, the economic issue extends beyond the initial payment.
A permanent easement can reduce future flexibility. It may limit where an owner can build, alter the character of a property, and remain attached to the land after it changes hands. For residential property owners, that is a direct wealth issue. For industrial and land investors, it is a reminder that infrastructure can create value on one tract while imposing constraints on another.
This is where the AI buildout starts to look less like a pure technology story and more like a classic land-use conflict. The benefits are broad and often abstract: growth, jobs, tax base, grid investment, and digital capacity. The costs are immediate and local: visual disruption, loss of property control, construction impacts, and concern that ratepayers will ultimately subsidize facilities built for some of the world’s largest companies.
The political discount is coming to data-center valuations
Georgia Power has argued that large-load customers will pay more, helping put downward pressure on residential rates. The utility projects nearly $102 in annual savings per residential customer beginning in 2029 from its broader approach. Whether that outcome materializes will matter enormously to public acceptance.
For now, though, the political risk is clearly increasing. Georgia lawmakers previously voted to suspend new data-center tax exemptions in 2024, although Governor Brian Kemp vetoed the measure. A December 2025 evaluation from the University of Georgia’s Carl Vinson Institute of Government projected a negative net fiscal impact of nearly $574 million from the state’s data-center sales-and-use-tax exemption.
Investors should not read that as a verdict that data centers are bad investments. They should read it as a warning that the policy assumptions behind the trade are getting more fragile.
The early data-center investment thesis depended partly on a bargain between states and capital: developers would bring construction spending, tax revenue, and technology investment; governments would provide incentives, speedy approvals, and infrastructure support. That bargain becomes harder to sustain when communities see a relatively low-employment facility consuming vast amounts of electricity while new transmission routes cut through private land.
That does not mean data-center development stops. It means the highest-quality projects will increasingly be those that can demonstrate tangible local value and credible infrastructure financing—not merely a large capital-expenditure number in a press release.
The contrarian take: power scarcity may improve the best assets
Here is the overlooked upside for investors: the same friction that complicates development can strengthen the value of already powered, entitled, and connected sites.
Markets tend to overreact to either side of a supply story. During the early phase of a boom, capital assumes every attractive market can produce unlimited supply. In the next phase, reality intrudes: transmission constraints, water availability, interconnection queues, equipment lead times, local resistance, and permitting all slow the pipeline.
That is not necessarily bearish for existing data-center real estate. It can be a competitive moat.
A facility with contracted power, durable utility relationships, available expansion capacity, and a completed entitlement process is worth more than a comparable-looking parcel that only has favorable zoning and a glossy development plan. The market may still call both “data-center land.” Sophisticated capital should not.
This will create a sharper split inside digital infrastructure. Prime assets in power-secure markets may command premiums because replacement supply is harder to build. Peripheral sites could look deceptively attractive until the cost and timing of grid upgrades are fully understood.
The same distinction applies to REITs and infrastructure funds. The right question is no longer simply how much data-center capacity a platform owns or plans to deliver. It is how much of that capacity has firm power, what expansion requires, who bears upgrade costs, and how exposed the portfolio is to community and regulatory conflict.
What this means for you
For real estate operators, power diligence now belongs ahead of land acquisition, not after it. Ask for written clarity on available capacity, interconnection status, upgrade obligations, construction timing, curtailment exposure, and the contractual allocation of costs. A site-control agreement without a credible power path is not a development pipeline; it is a speculative land position.
For investors, distinguish between operating capacity and promotional capacity. Existing, energized facilities deserve a different valuation framework from proposed campuses that depend on future utility upgrades. Favor management teams that discuss grid strategy with the same precision they use for leasing and capital structure.
For landowners, a transmission proposal is not just a one-time acquisition conversation. Easement language, access rights, future infrastructure rights, maintenance obligations, and resale implications can matter as much as the headline price. The asset is not only the land beneath the tower; it is the flexibility of the land around it.
For local governments, the lesson is equally direct. Data centers can be economically valuable, but incentives should be tied to transparent infrastructure commitments, cost allocation, community protections, and measurable public benefit. The next political backlash will not be driven by opposition to AI itself. It will be driven by residents who believe the physical costs of AI arrived at their doorstep while the financial upside went elsewhere.
The data-center boom is real. But the winning real estate strategy is changing. In this market, the most valuable property may not be the parcel with the best location. It may be the one with the cleanest, fastest, and most politically durable path to power.