U.S. Treasury’s $40 Trillion Debt: What Founders Should Do Now
America hit $40.047 trillion in debt. Pretending that number is harmless has become Washington’s most expensive habit.
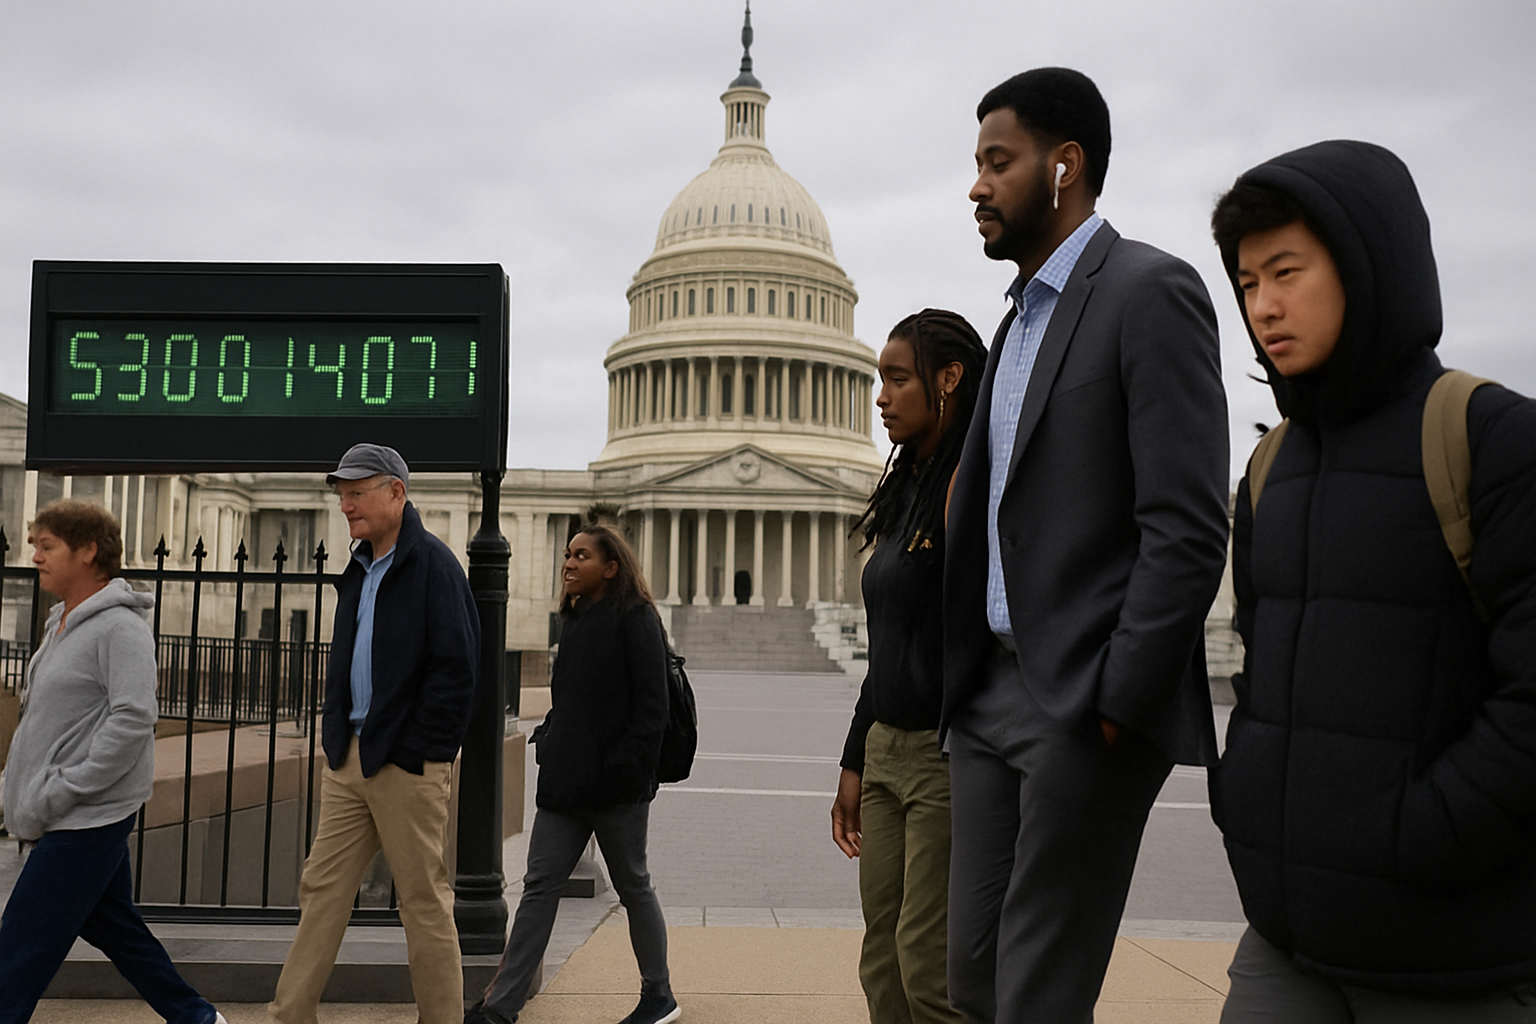
America hit $40.047 trillion in debt. Pretending that number is harmless has become the most expensive habit in Washington.
On August 18, the U.S. Treasury’s total public debt outstanding reached $40.047 trillion. That is not a political talking point, a scary chart for cable television, or a reason to sell everything and move into tinned food. It is a bill—and the interest meter is now running fast enough to change what America can afford to do next.
$40 trillion arrived faster than anyone should be comfortable with
The ugly bit is not merely that the debt crossed a round number. Round numbers are for headlines. The real issue is speed.
The U.S. hit $38 trillion in October 2025, $39 trillion in March 2026, and now $40 trillion in August 2026. That is roughly $2 trillion added in about 10 months. You do not need to be a macro genius to understand the direction of travel.
Of the $40.047 trillion total, about $32.266 trillion is debt held by the public—investors, banks, pension funds, foreign governments, the Federal Reserve and everyone else who owns Treasury securities. Another $7.782 trillion is held within the government, largely by trust funds such as Social Security.
People love to wave away the intragovernmental number because the government “owes it to itself.” That is technically neat and economically incomplete. Those trust funds represent promised benefits. Calling them fake debt because one arm of government owes another is like saying your mortgage does not count because you and your bank both exist in the same country.
This debt did not appear because one bloke in Washington woke up and made a bad call. It piled up under both parties, through tax cuts, spending programs, pandemic rescue packages, wars, ageing demographics and the political refusal to disappoint anyone who votes. Reuters estimates debt rose roughly $11.6 trillion over Donald Trump’s two terms and about $8.4 trillion during Joe Biden’s four years.
Everyone wants the upside of government spending. Almost nobody wants to say which bill should shrink, which tax should rise, or which benefit promise needs to be redesigned. That is how you get to $40 trillion: not through one spectacular failure, but thousands of very popular decisions made without an adult financing plan.
The debt number is not the problem. The cost of carrying it is.
A country as large, productive and wealthy as the United States can carry an enormous debt load. America borrows in its own currency, has deep capital markets and still enjoys exceptional demand for Treasuries. Anyone telling you a $40 trillion headline means instant collapse is selling fear, usually with a newsletter attached.
But the “therefore it does not matter” crowd is just as unserious.
Debt becomes dangerous when the cost of servicing it begins swallowing the room. Old Treasury debt issued during the cheap-money years is steadily maturing. It must be refinanced at today’s higher interest rates. That is the sting. Governments rarely pay down debt in one dramatic cheque; they roll it over. And every rollover at a higher rate turns yesterday’s cheap borrowing into tomorrow’s fixed cost.
Congressional Budget Office projections put net interest costs at roughly $1 trillion in 2026. In plain English: America is on track to spend around a trillion dollars a year just for the privilege of having borrowed in the past.
That spending does not build a bridge, train a worker, fund research, buy defence equipment or improve a child’s education. It pays holders of government debt. Some of those holders are American retirees and institutions, so it is not money vanishing into the desert. But it is still money politicians cannot deploy elsewhere without borrowing even more.
That is the crowding-out problem. It is boring right up until it is not.
Why founders and investors should care about a government balance sheet
Most business owners make the mistake of treating federal debt as a faraway national issue. It is not. The government’s borrowing costs set the background price of money for everyone.
If investors can get attractive yields from U.S. government bonds, they demand higher returns from everything else: venture capital, private credit, commercial property, small-cap equities and your next expansion plan. A business that looked brilliant when money cost 2% can look ordinary when capital costs 7% or 10%.
This matters most to businesses that require external funding to survive long enough to become good. The era of raising a ridiculous seed round with a deck, a buzzword and a founder in a black skivvy is already behind us. A structurally higher cost of capital makes it harder still.
For investors, it means valuation matters again. When the risk-free return rises, you should not be paying fantasy prices for businesses with vague profits promised in 2031. Plenty of clever people learned this the hard way when rates rose after 2021. They will apparently need to learn it again.
For operators, the practical consequence is brutally simple: cash flow beats charisma.
A company with pricing power, sensible debt, repeat customers and a real margin can handle a tougher capital environment. A company dependent on another funding round to pay for last year’s promises cannot. This is not pessimism. It is just arithmetic wearing work boots.
The overlooked angle: $40 trillion does not automatically mean a Treasury crisis
Here is the contrarian bit. The debt headline is serious, but it is not a stopwatch ticking down to an inevitable American default.
The United States has extraordinary advantages. Its economy is vast. The dollar remains the world’s dominant reserve currency. Treasury markets are still central to global finance. And the country has taxing capacity that would make most governments jealous.
The question is not whether America can pay a coupon next month. Of course it can.
The question is whether Washington can stop running deficits large enough to make debt rise faster than the economy over a long period. That is a political problem before it is a market problem.
There is also a distinction people routinely butcher: gross debt is not the same as debt held by the public, and debt alone is not the same as debt relative to economic output. The latter is more useful for judging sustainability. But do not use that distinction as a sedative. Debt held by the public is already around the size of annual U.S. economic output, and CBO expects it to keep climbing as a share of GDP over the coming decade.
A country can grow its way through a lot of debt if productivity rises, investment is strong and fiscal discipline eventually shows up. But “eventually” is doing some very heavy lifting when the interest bill is growing faster than political courage.
The likeliest damage is not a Hollywood-style default. It is a slow squeeze: more money devoted to interest, more pressure for financial repression or inflationary policy, greater sensitivity to bond-market tantrums, and less room to respond when the next recession, war, disaster or banking wobble turns up.
That is the cost of arriving at a crisis with no spare capacity.
Washington’s favourite lie is that growth alone will fix it
Economic growth helps. Obviously. A larger economy generates more taxable income and makes existing debt smaller relative to GDP.
But growth is not a magic spell. If spending commitments, interest costs and deficits grow just as fast—or faster—then a booming economy simply gives politicians a bigger platform from which to borrow.
The White House argues it is focused on cutting waste, fraud and abuse while accelerating growth to improve the debt-to-GDP ratio. Fair enough as an ambition. Every government should cut waste. But waste is not remotely large enough to close this gap by itself, and nobody should pretend otherwise.
A credible solution requires choices that are all unpopular with someone: restraining spending growth, redesigning entitlement programs, raising more revenue, growing the economy faster, or some ugly blend of all four. The longer politicians avoid those choices, the more likely investors force them later through higher borrowing costs.
Markets are patient until they are not. Ask Britain how quickly a bond market can become an unpaid adviser with a very bad bedside manner.
What this means for you
Do not react by trying to trade every debt headline. That is punter behaviour, not investing.
Instead, use the $40 trillion milestone as a prompt to make your own financial life less fragile.
First, audit your debt. Know exactly what floats, what resets, what is fixed and when it matures. If your business only works because rates never rise again, you do not have a business model. You have a weather forecast.
Second, build a proper cash buffer. Not “we have a credit line” cash. Actual liquidity. Credit lines are wonderfully available right up until the moment lenders become nervous.
Third, demand real returns from your investments. A government bond yield changes the hurdle rate. If you are taking equity risk, illiquidity risk or startup risk, make sure the potential reward justifies it.
Fourth, favour businesses that can self-fund. I love ambition. I am building Agave Finder because I intend to make it enormous. But ambition without unit economics is expensive theatre. In a higher-for-longer world, businesses that turn revenue into cash get options. Businesses that burn cash lose them.
And finally, ignore anyone claiming $40 trillion means nothing—or everything. Both are lazy answers.
It means America has less margin for error. That is plenty consequential. The smart response is not panic. It is to run your household, portfolio and company like money will cost something again—because it does.